
This weekend, my eldest daughter, Anneke, graduates from university.
Right now she is celebrating in Punta Cana with 120 of her closest friends.
So no, she is not thinking about first-time homebuyer strategy at the moment.
But here’s why I am thinking about it for her.
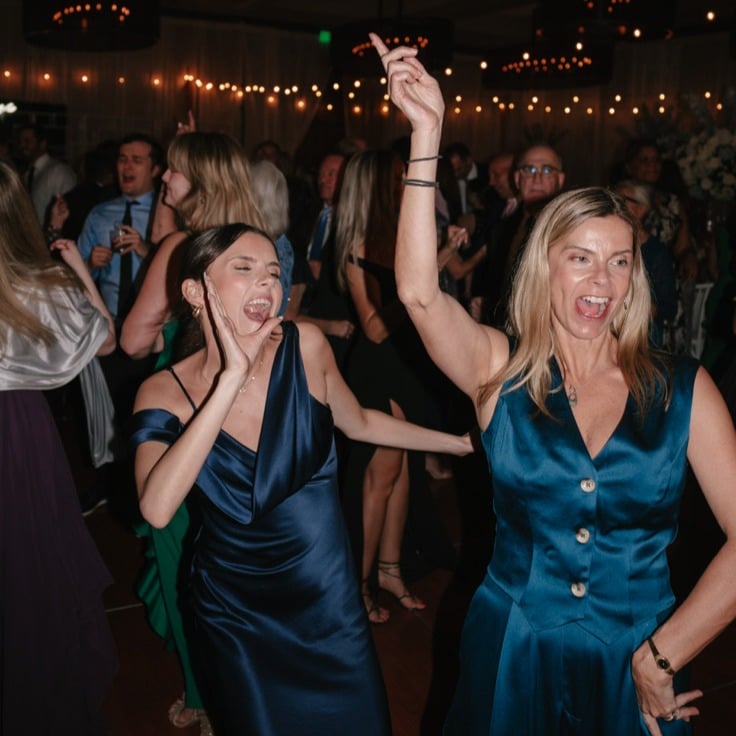
When her RESP came up short in her final year, Anneke didn’t ask for help.
She got a job. She paid her own tuition. She covered her own rent.
And when she was done?
She had enough saved to book and pay for this grad trip herself.
She leaves university with a great job at the bank. She’s already started contributing to her RRSP.
And recently, when I asked her how she was feeling about her financial future, she didn’t talk about AI and job security.
She told me she was most worried about her inability to buy a home.
And this is why our next money conversation is going to be around the First Home Savings Account (FHSA). You’re welcome kid!
Because Anneke is exactly who it was designed for.
What the FHSA actually is (in plain language)
In my opinion the FHSA is one of the most useful financial tools available to young Canadians right now.
Think of it as a hybrid between the RRSP and a TFSA
- Contributions are tax-deductible (like an RRSP)
- Withdrawals for a home purchase are completely tax-free (like a TFSA)
- You can contribute up to $8,000 per year, to a $40,000 lifetime max
- Unused room carries forward
- If you don’t buy a home, it can roll into your RRSP without penalty
It is one of the few places in our Canadian system where you get tax efficiency upon contribution and withdrawal.
The one thing most new grads don’t know
The clock starts when you open the account.
In this example if Anneke waits, she loses contribution room for that year.
So I will be encouraging and perhaps contributing to her opening it early. Even if only $100!
This will lock in the room for her. Essentially starting the clock. that will create options for her later.
How it works alongside an RRSP
As previously mentioned, Anneke already has an RRSP which many new grads are familiar with.
For someone thinking about a first home, I believe the FHSA deserves attention first.
That said, the real opportunity is how they work together.
Through the Home Buyers’ Plan, you can withdraw from your RRSP toward a home purchase.
Layer that with an FHSA, and you’ve created a meaningful down and tax efficient payment strategy.
One strategy most people miss
If you’re starting a job mid-year, like Anneke, your income is lower now than it will be in the years ahead.
The FHSA allows you to contribute now and claim the tax deduction later.
This matters because the value of that deduction increases as your income grows.
It’s a small planning detail that can make a meaningful difference in higher earning years.
The simple game plan
If you’re a parent of a new grad, this is the conversation:
Now: Open the FHSA. Deposit what you can. Lock in the room.
Year 1–4: Contribute consistently. Build the habit. Let it grow.
At purchase: Use the FHSA tax-free. Layer in RRSP strategies if appropriate.
I have to be honest I am going to be a complete mess when I see Anneke walk across the stage on Sunday. I am so stinking proud of her. She worked hard not only at school but also in navigating life which we all know isn’t easy to do.
Yes she learned about accounting (whippee an accountant on the team!) but she also learned time management and how to manage money while she was still in school. These are skills that will set her up for life.
And dont get me wrong, she is my daughter so she played hard too. Creating friendships that will last a lifetime. I am going to miss the women of Braemar Drive!
Anneke, If you happen to read this between poolside drinks, know you mean the world to me and all those money talks that you called “toxic” well babe I think they paid off!
Have fun in Punta Cana kid, you deserve it and when you get back we are going to have “the FHSA talk”
xoxox
Mom
P.S. And if you are thinking about a new grad gift what about a FHSA contribution?

